Distributions, price return and declared cash
Separate price-only change, gross cash, actual entitlement and net accounting rather than promising a dividend offset.
A distribution label is not a payment record
An announced distribution can have an amount, eligibility, effective dates and payment conditions. An actual account cash receipt is another source. The cash lens accepts gross declared cash per original share solely for a fixed arithmetic comparison. It does not verify ownership, entitlement, withholding, tax, payment, settlement or availability for another purchase. The original shares remain the input basis even if the split ratio changes displayed units. All inputs use one assumed cash unit. A real multicurrency position, short distribution obligation or reinvested quantity path needs other contracts and cannot inherit the long-share example by changing its label.
The neutral teaching case names the offset
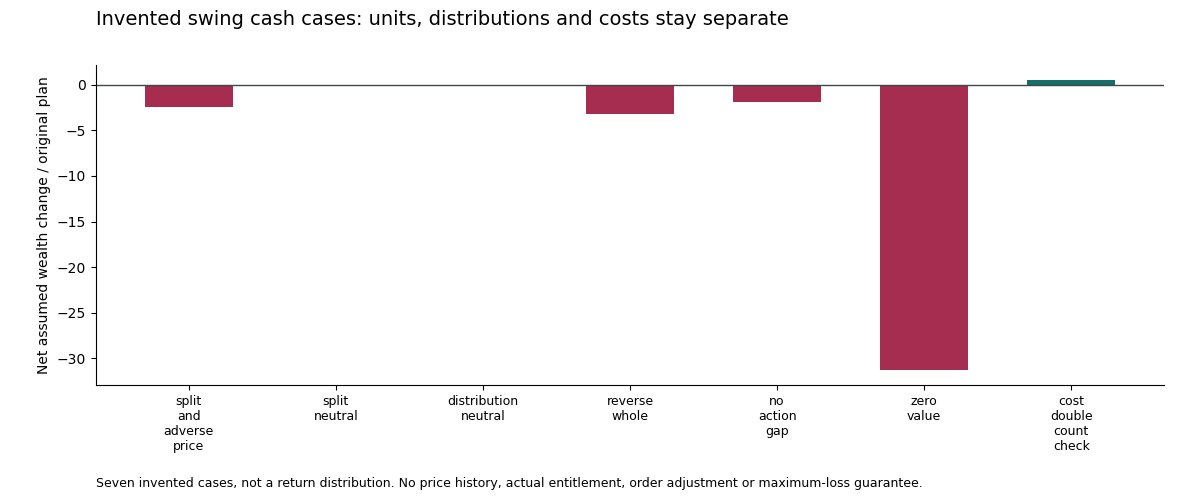
The invented distribution-neutral case has 100 original shares, entry 100, no split, post price 99 and gross cash 1 per original share with zero cost. Price-only change is -100 and declared gross cash is 100, giving zero assumed wealth change. This is not a prediction that an actual ex-date price drops by the distribution, or that a particular account receives it. It is a completed equation with explicit quantities and scope. Keeping it separate from the neutral split demonstrates that unit conversion and cash addition are different operations. A lower chart price or a published amount cannot alone establish actual net economic gain.
Gross, net and price-only need named inclusions
The adverse-price default has -800 price-only change,50 declared gross cash and 20 declared cost. Gross assumed change is -750 and net is -770. If a source price series already includes a distribution adjustment, adding separate cash may duplicate its convention. If a source ledger already deducts the entered cost, deducting it again would likewise change meaning. Preserve actual source inclusions, costs and original denominator before combining figures. The workbook offers exact JSON/CSV references and independent Decimal arithmetic, not real entitlement or account certification. No software result can settle absent tax or broker evidence, even when the numbers are internally consistent.
A delayed payment is not automatically usable cash
Actual economics can distinguish accrued entitlement, paid balance, settlement and spendable funds under account rules. The tutorial does not model those times or finance another trade from the declared distribution. A fixed original position is held for arithmetic, and the user chooses a valuation price manually. A real portfolio needs complete positions, actual cash flows and execution state rather than a sequence of favourable payouts. The site invents no paid study, representative user population or profitable winner from these examples. Preserve actual event sources and the authorised independent research process before turning a teaching offset into a model-performance or suitability claim.
Filled fictional swing case
The complete neutral equation is -100 price plus 100 declared gross cash equals zero before cost, under invented inputs. The default's separate adverse branch ends at -770 after its one cost. Neither case establishes a real payout, ex-date behaviour, tax or spendable balance. The completed conclusion is a named cash-accounting convention with actual entitlement and execution sources still absent rather than a dividend strategy forecast.
| Object | Record | Bounded finding |
|---|---|---|
| Price-only | -100 neutral case | Separate from cash |
| Gross declared cash | 100 | No entitlement proof |
| Net adverse case | -770 | Different authored branch |
Primary references and scope
Expanded source review: 13 October 2026. Documentation supports the stated mechanism, not a tested account, hypothetical fill or provider outcome.